Keeping up-to-date records of your business transactions isn’t the most glamorous part of being an entrepreneur, that’s for sure. But, in reality, having accurate and up-to-date digital bookkeeping is one of the core ways to control your finances (and your business).
Digital bookkeeping is the future of your finance
The digital age has revolutionised how many business owners carry out their bookkeeping. From digital accounting to real-time data, the modern bookkeeper is now equipped with many tools and resources. These tools make the job easier, more efficient, and (crucially) less time-consuming.
When your bookkeeping goes digital, that means:
Your data entry process gets automated – receipts, invoices, and other supporting documents can all be scanned using OCR software. This gives you a digital copy of the paperwork, digitises the data, and pulls it into your online ledgers. There’s no need for tedious manual data entry, and you also reduce the chances of human error.
Your digital records are available 24/7 in the cloud – instead of searching through messy hard drives or dusty filing cabinets, all your financial documentation is available at the press of a button. You can pull up the documents you need anytime from any location with internet access. And everything is safely encrypted and backed up.
Your tax returns can be filed digitally – with all your bookkeeping data saved and accessed via your cloud bookkeeping/accounting software, your tax returns become much more straightforward. Whether it’s quarterly GST/VAT or annual corporation tax returns, you have all the data the tax office needs ready to send in a digital format.
Your finance data goes real-time – scanning and digitising your receipts when you make the transaction doesn’t just keep your records up to date. It also gives you real-time data on all your income, expenditure, and operational costs. Instead of working with management information that’s months out of date, you’ll have informative real-time data. With this data you can safely base all your big business decisions.
You’re 100% in control of your finances – by embracing the benefits of digital bookkeeping, you kick your finances into shape. You and your finance team have accurate real-time records of all income and outgoings. So you can stay in complete control of the financial management of the business. Your accounts are in tip-top shape, and you’re ready to file your tax returns whenever necessary.
Talk to us about switching to digital bookkeeping
If you want to transform your bookkeeping, now’s the ideal time to go digital.
Talk to our team and determine what bookkeeping or accounting software is right for your business.
Once you see the efficiency, accuracy, and long-term benefits of digital bookkeeping, you’ll understand why going digital is a no-brainer, whatever type of business you run.
Small businesses are particularly vulnerable in tough economic times. How can you keep your cashflow strong?
When sales are slow, overheads and salaries still need to be sorted. Pre-planning and being proactive can help you weather tighter economic periods and allow you to continue to thrive.
Ensure you have a clear picture of your payroll and any other planned expenses that must be accounted for.
If there’s even a possibility of a shortfall, it’s essential to meet this head-on. Whether this means talking to your supplier or creditors to figure out an arrangement or compromising on other business outgoings, you must make a plan to ensure that the business, or your staff, won’t suffer.
Minimise the stress of cashflow
Invoice early – Send any invoices you can, in advance, if possible. Perhaps consider whether you have any regular clients or customers that you could offer a retainer or similar deal if they book services or make a purchase from you in advance.
Chase payment – Use this opportunity to chase up any outstanding payments. Strong communication and relationships matter – talk to clients and chase invoices.
Talk to suppliers – A little honesty can go a long way. Perhaps they can extend a line of credit for your payments to them. In most cases, a good supplier would rather offer a little flexibility to keep an ongoing business relationship.
Review Inventory – Can you find a cheaper supplier locally to avoid the shipping costs or discuss alternative products that allow you to reduce expenses?
Review your costs – It’s also a good idea to do a general review of expenses. Business costs can creep up, and it’s a great idea to make a time to check on your expenses regularly, no matter what your financial situation. Review all of your regular payments and subscriptions as well as upcoming costs. There may be travel, functions, or purchases to which you can decide on an alternative approach.
Talk to the bank or tax department – If cashflow is tight, ensure you have conversations early, so you have everything in place to see you through.
We can help you implement strategies to protect your business for the long term and help you alleviate cashflow worries and keep your cashflow strong through tough times.
International Business in Australia – When to Register for GST
Does your international business make sales in Australia? You may need to register for Australian goods and services tax.
Like many countries, Australia charges a goods and services tax (GST) on most products and services sold within Australia. Australian GST is a tax of 10% added to the price of goods and services.
Any business that makes sales within Australia needs to consider whether it should be registered for GST and include GST in its prices.
Suppose your business does need to register for GST. In that case, it must submit a business activity statement (BAS) to the Australian Taxation Office (ATO) and pay the GST amount.
When should an international business register for GST?
If your business makes sales of AUD $75,000 or more per year (or $150,000 if it’s a non-profit organisation) you must register for GST with the ATO.
There are some exemptions to registration, and you’ll also need to assess your GST turnover. Not all income is included in the GST turnover threshold.
Some examples of goods and services that can incur GST include digital products. Such as ebooks or training courses, professional advisory or consulting services, and personal products such as clothes or jewellery.
Overseas businesses can choose from simplified or standard GST registration, although there are criteria for simplified registration.
Australian business owners can check the ABN Lookup website to see if an overseas supplier you interact with is registered for GST. Remember, you can only claim GST on expenses if a GST-registered business has correctly charged it. And if you provide your ABN to a GST-registered overseas business, they do not need to charge you GST for business purchases. So check that you’re not claiming GST incorrectly by inspecting the invoices provided by the supplier and the ABN Lookup.
If your international business transacts in Australia, we can help determine if you should be registered for GST in Australia. We can also inform you about the invoicing requirements and the BAS process.
Having proper control of your business finances is a big advantage. It helps you make well-informed business decisions and keeps your organisation profitable.
With so many digital tools for managing your bookkeeping, accounting, and management reporting, it’s never been easier to manage, track and forecast your financial position.
But what are the primary tools you need? And how do you set up your financial systems, apps, processes and reporting to put yourself back in the finance driving seat?
1. Bring your bookkeeping into the digital age
Digital bookkeeping apps are a great way to digitise your receipts, records, and source documents. This saves a lot of time at year-end and makes it much easier for you to keep track of your company’s finances and accounting. Keeping your receipts in a box to manually enter at period-end is no longer enough. Take the next step and digitise your receipts at the source, so you have up-to-date digital records and copies of source documents.
Optical character recognition (OCR) software, like Dext Prepare or Auto Entry, scans the receipt, converts it into a digital format, and stores it in the cloud.
2. Do your accounting in the cloud
Cloud accounting is a software-as-a-service (SaaS) solution that helps you carry out all your main accounting and financial management online without installing any software.
Cloud accounting providers, like Xero, QuickBooks, MYOB, or Sage, design their accounting platforms to take the pain and hassle of business accounting. You get all the tools and features you need to work on your accounting tasks. And your platform provider will also take care of all the data storage, backups, and security of your data.
A good cloud accounting platform does more than just save your hard drive space. It also provides you with tools and dashboards that improve your access to management information, financial reporting, forecasting and projections, performance tracking, and more.
3. Use the latest in expense management tools
Expense management can be a time-consuming and tedious job. But it’s also a vital task that helps you ensure you’re spending company money wisely and not overspending. If employees start exceeding their budget limits, this can be a costly mistake for the company and your cash flow.
Expense management tools, such as Soldo, Weel, or Pleo, help you manage staff spending by giving employees virtual cards linked to a specific budget, account, and code. This lets you track their expenses easily and ensure they stay within their budgeted limits. These platforms also give you detailed reporting and analytics to see where money is being spent and where savings can be made.
4. Make it easy to accept digital payments
Slow payment is one of the most frustrating things for small businesses. If your customers don’t pay on time, this can result in a loss of revenue, poor cash flow, and an inability to cover your basic costs and overheads. To resolve this issue, many companies have begun to switch to digital payment platforms that make it simpler, faster, and easier to collect payments.
Payment platforms like PayPal, Square, or Stripe offer faster payment times and more control over the customer experience. Some platforms even integrate with your cloud accounting, so you get automatic bank reconciliations.
5. Embrace the latest in digital reporting and forecasting
With digital accounting changing so rapidly in recent years, there’s never been a better time to embrace the benefits of the latest in digital reporting and forecasting.
Economic conditions are hard to predict. So, it’s crucial to quickly analyse data, check your performance and make predictions about how your company will fare in the coming months. When you use cloud solutions for financial reporting and key metrics, you can monitor trends in real-time while accessing the data anytime, anywhere.
Having this information at your fingertips helps you make informed decisions faster than ever before, which translates into more sales, increased business growth, and bigger profits.
Talk to us about updating your financial systems
If you want to give your finances a touch of digital magic, please come and talk to us.
We can walk you through the best cloud platforms, fintech apps, and business tools to add to your app stack – so you’re ready to make the most of a digital approach to your finances.
Inventory Accounting is keeping track of your inventory, the time it takes to sell, and the profit made on each product. It is essential to track inventory if you want to manage your business effectively.
What counts as inventory?
Inventory is anything you buy to on-sell, including fully-completed items to sell in your store, products you install in people’s homes or businesses, or materials used to manufacture products.
Work equipment, tools, or anything else used in your business don’t count. If you have a drop-shipping business where third-party suppliers ship direct to your customers, you don’t have inventory either.
Accounting for inventory
Tracking the movement and value of your inventory is essential for pricing, insurance, accurate tax returns, and selling your business.
Good inventory tracking can also help you:
Manage stock levels – order more popular items and fewer slow-moving products
Identify profitable items and true margins
Find bulk discounts on popular items
Boost marketing by identifying sales trends. It all adds up to less waste and better cash flow – which means more money for business-building activities.
Start accounting for inventory now
To manage your inventory effectively, you need to track how much you have, how much it costs, and how much you sell it for. You must also factor in discounts, transport and storage costs, damage, and write-offs. It can get pretty complex – so you might want to get help from people who have done it all before.
Want to build a better understanding of your inventory? Get expert help from our accounting team.
Budgets Are Boring! 5 ways to spend less without one.
If you hate budgets and budgeting and find it sooo boring, how can you easily cut your spending?
Here are five ways to save without tracking every transaction:
Review your subscriptions – Your fixed outgoings are the easiest way to cut back: big outgoings like your insurance, power, phone and entertainment subscriptions. If you can reduce or eliminate even a few of these, you’ll make an immediate difference to your spending.
Embrace low-cost social activities – A night of drinking and dining out is fantastic fun, but it’s also costly, so try to make it an occasional treat. Instead, check out the free and cheap activities in your area and swap an expensive night out for a more cost-effective option.
Have a zero spend day – Pick one day a week, or one day each fortnight, and try to spend nothing. Make your own food and coffee, stay away from the shops and don’t add anything to your cart.
Plan your meals – Groceries have shot up in price over recent years. Planning your meals for the week and shopping accordingly means you can spend less and buy fewer takeaways.
Pay yourself first, then live off what’s left – Pay a realistic amount into your investments, savings or debt reduction first, advises the author of Automatic Millionaire. Then pay your commitments, like the utilities. Whatever is left over, live off that. If you’re not sure how much to pay yourself, we can help.
Confession Time… We Love Budgets!
We actually love budgets, even though they have a boring reputation. They’re part of the spreadsheet family, and you know that spreadsheets are close to our hearts.
While you can save money without a budget, if you embrace one it can turbocharge your success. There are apps to make it easier and support your saving goals.
So whether you want help with saving, or a budget for your personal life or your business, we can definitely give you a hand. Get in touch, we’d love to hear from you.
Understanding your business breakeven point is essential to know how much money you need to make to stay in business. It can therefore help you make well-informed financial decisions and practical business plans.
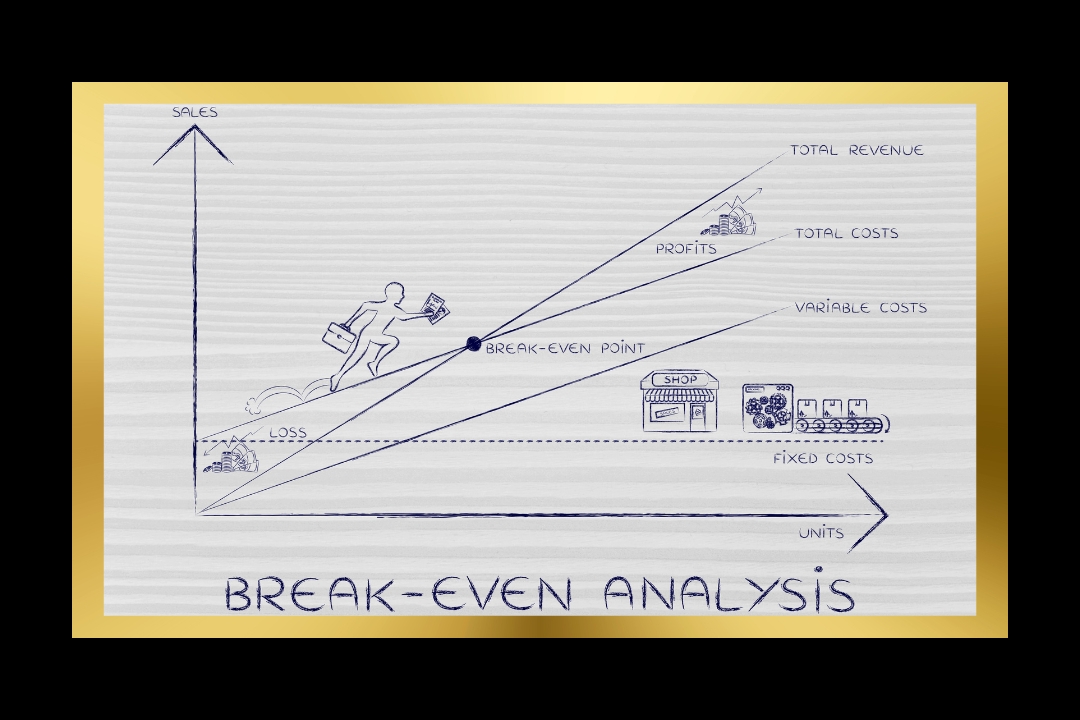
The breakeven point is the income or sales needed to cover all costs. Any earnings above this point generate profit. So your breakeven point tells you the minimum sales required to continue operating a viable business.
Understanding the breakeven point in conjunction with financial reports can give you valuable data to analyse fixed and variable costs and set sales targets for the business or individual staff members.
Fixed and Variable Costs
Fixed costs – remain the same regardless of how many sales you make. Expenses like rent, equipment lease repayments, or full-time staff must be paid whether you sell any goods or services or not. Fixed costs are often called overheads.
Variable expenses – (sometimes called production costs) fluctuate based on sales. For example, the cost of goods sold, production labour, and commissions paid to salespeople will vary according to the number of goods or services sold.
It’s helpful to work out an amount or percentage of variable costs compared to the sale price of your products or service. This may not be exact initially, but even if you get a rough figure to work with, this will help calculate your breakeven point. Over time as you analyse your financial reports, you’ll be able to refine the calculation and adjust your selling price accordingly.
How to Calculate Breakeven
You’ll need to know your fixed costs (overheads), selling price, and production costs.
One common method of calculating breakeven is as follows:
Overheads / (selling price – production cost)
For example, let’s say monthly overheads (rent, vehicle lease, administration staff) are $20,000, and you sell a coaching program for $3,000 with variable costs (coach fees, handout materials for participants, advertising) of $1,500 per program.
$20,000 / ($3,000 – $1,500) = 13.33
You would need to sell over 13 programs per month to break even, which equates to $40,000 worth of sales.
If the same program had variable costs of $1,800, you would need to sell 17 programs per month to generate $50,000 worth of monthly sales just to cover costs. Variable costs of $1,000 per program would mean you only need to sell 10 per month to break even.
With these examples, you can see how important it is to understand your fixed and variable costs. Then you’ll know exactly how much you need to make to remain in business and the resulting impact on your financial position. Once you have a reasonably accurate breakeven figure, you can quickly calculate your profit before tax for sales above the breakeven point. In the example where variable costs are $1,500 per program, let’s say you sell 20 programs each month. This would result in an extra $10,000 in profit (before tax) after paying for overheads and variable costs.
Can breakeven help with your pricing?
Understanding your breakeven point can give you some deep insights into your selling prices, helping you understand if they’re realistic.
For example, if your variable costs are high, how much more income will you need to reach breakeven? Is there a fair price for consumers that covers your expenses in a reasonable time frame? Do you need to raise prices to account for fixed and variable costs accurately?
Talk to us about calculating your breakeven point
There are different ways of calculating your breakeven point to confirm the viability of your business and the ideal pricing point for driving both sales and profitability.
We’d love to help you understand your business financials in more depth so that you can plan for long-term sustainability, enjoyment, and profitability.
Starting from the 2023 financial year, there are new rules for keeping records and calculating deductions for people who are working from home. There are now two ways to work out your deductions: the actual cost method and the revised fixed rate method. The revised fixed rate method has been changed to make it easier for people to calculate their expenses and avoid complicated calculations.
Using the revised fixed rate method, you can claim 67 cents for every hour you work from home. This covers things like; electricity, gas, phone and internet usage, computer consumables, and stationery. You can also claim the work-related portion of any equipment you bought for your home office, like furniture or technology.
You don’t need to have a dedicated home office space to use the revised fixed rate method, and businesses that operate from home can also use it to claim home-based business expenses.
To use the revised fixed rate method, you must keep a record of the total number of hours you worked from home, as well as evidence that you paid for the expenses covered by the fixed rate method, like phone or electricity bills. You also need records for any equipment you bought to work from home.
Please feel free to download and use the document below to record the hours you worked from home.
New rules for tax deductions on working from home expenses from the 2023 financial year.
Dedicated workspace no longer required to claim deductions.
Depreciation on work assets such as office furniture and technology can be claimed.
Two calculation methods are available: actual cost method and revised fixed rate method.
Revised Fixed Rate Method Highlights
Expenses covered under the revised fixed rate method: electricity, gas, phone, internet, computer consumables, and stationery.
Rate for revised fixed rate method increased from 52 cents to 67 cents per hour worked from home.
Businesses that operate from home can also use the revised fixed rate method.
To use revised fixed rate method, records of hours worked and expenses.
If you have worked from home during the 2024 financial year, contact us to discuss your situation further as you are likely to be affected by the above changes.
Additional Resources:
ATO Instructions for claiming deductions using the revised fixed rate method or actual cost method, click here.
Transforming into a digital and cloud business sets the best possible infrastructure for future growth. And, as your business scales, the benefits of going digital will become apparent.
Running your key business processes in the cloud and using the latest digital software and apps adds to your efficiency and productivity. And most importantly, digital systems are designed to scale with you as your enterprise grows and the need for resources increases.
Here are some significant reasons for taking the plunge and diving into digital.
Automate your key manual process to increase efficiency
A scalable business has to systemise its processes and procedures. Is your business model still tied to manual processes and a system that only exists in the owner’s head? If so, you’ll eventually come up against a capacity brick wall. Therefore, systemising and automating your processes is a fundamental step when you jump to digital.
Look at every internal and external step in your operations and write down how these systems work. Note down each task, who actions what, and how the whole system links in with the next step in your operational chain. If there are opportunities to automate a step, automate it. Many business apps now include artificial intelligence (AI) or automation features that can chase up unpaid invoices, send automated replies to customers in live chats, or take automatic payments, etc.
Work in the cloud to stay more connected
Since the start of the 2020 pandemic, the world has seen a quantum shift to remote working – and that’s only been possible because of cloud technology. Instead of working from local applications on our laptops or office-based servers, most tech-savvy businesses now use cloud-based apps that are accessible anywhere you have an internet connection.
Switching to cloud-based systems is a game-changer. You and your team are no longer tied to a physical office and can be productive from any WiFi-enabled location. That could be your home, customer’s warehouse, regional office, or local coffee shop. And the benefits aren’t just limited to remote working. With your applications and databases in the cloud, you can access customer information, sales data, or financial numbers wherever you happen to be. Everything is securely backed up and available at the press of a button – that’s an invaluable benefit if you want to be flexible, connected, and scalable as a business.
Create your own custom app stack
Your business systems and software no longer have to remain static and based on the office server. By combining a business and accounting platform like Xero, MYOB, QuickBooks, or Sage with your own choice of business apps, you can create a truly tailored ‘app stack’.
Apps use an API (application programming interface) to connect with each other, share data and form a more extensive business system. This can include apps to:
Manage and automate your bookkeeping and accounting tasks
Send out e-invoices to your customers to speed up payments
Take automated payments and reconcile your transactions
Automatically chase late-paying customers and carry out credit control duties
Project manage your operations and provide detailed reporting
Manage your job utilisation and time spend on each project
Keep a detailed real-time inventory of your products
Send out marketing campaigns and social media posts to your audience
Interact more closely with your end customers and learn their habits
Record and track your business data
App integrations and a customer app stack don’t just improve your productivity. Because your apps are connected via APIs and share your business data, you also have access to a wealth of data, information, and reporting features.
Look in detail at your cash flow, expenses, and spending to improve your cash position. Take a deep dive into your sales and marketing information to determine your best (and most profitable) customers. Run projections and ‘What if…’ scenarios based on your historical data to forecast the future path of the business. There are plenty of ways to use this bountiful data to help you review, understand and improve your performance as a company.
Make better-informed business decisions
A business in the pre-computer age would have had very little information on which to base its decision-making. Annual accounts, cash flow statements, and some basic management information would have been available, but there was very little real-time data to refer to.
In the digital age, you can see every aspect of your company’s performance in real-time – and, in some cases, in the future. That’s a game-changer and something every business owner should use to improve strategy, financial management, customer experience, and business decision-making.
To summarise, a digital business:
Creates systems that are integrated and connected
Shares and records all your business data
Reviews, analyses, and finds insights into your business information
Connects with your customers in more meaningful ways
Makes better-informed business decisions as a result.
Get in touch to discuss embracing cloud tech and a digital business model.