Stay Safe This Tax Season: Guard Against Rising Tax Scams
As tax season approaches, business owners and employees alike need to be vigilant against a rising tide of tax time scams. Despite the proactive measures taken by the Australian Taxation Office (ATO) and the National Anti-Scam Centre (NASC), fraudsters continue to find new ways to deceive unsuspecting taxpayers. With a notable increase in ATO impersonation scams reported in recent months, it’s crucial to understand the tactics scammers use and how to protect yourself. This article delves into the prevalent scams, offers expert advice, and provides practical steps to avoid becoming a victim.
The Rise of ATO Impersonation Scams
Recent data indicates a troubling 31% increase in reports of ATO impersonation scams through various channels such as SMS, email, phone, and social media as tax time approaches in 2024. These scams often involve unsolicited contact where fraudsters pose as ATO representatives offering refunds, assistance with tax issues, or alerting taxpayers to suspicious activity on their accounts.
Despite the efforts of the ATO and NASC, which have resulted in over 5,000 fraudulent website takedowns and the blocking of 100 million scam text messages in the last quarter of 2023, scammers continue to evolve their tactics. This persistence underscores the need for heightened awareness and caution during tax season.
Understanding the Tactics of Scammers
Scammers use a variety of methods to trick taxpayers into divulging personal information or transferring money. Some common tactics include:
– Phishing Emails and SMS: These messages often contain links to fake websites designed to steal personal information or install malware. The ATO has responded by removing hyperlinks from all outbound unsolicited SMS to prevent such scams.
– Phone Scams: Scammers might call, posing as ATO officials, and create a sense of urgency, demanding immediate payment to avoid penalties or legal action.
– Social Media Scams: Fraudsters may use social media platforms to contact individuals directly, offering tax refunds or threatening legal consequences.
Real Stories, Real Risks
Consider the case of John, a small business owner who received an email that appeared to be from the ATO, claiming he was due for a significant tax refund. Excited, he clicked the link and entered his personal and financial details. A week later, John discovered his bank account had been drained, and his personal information was used to open fraudulent accounts in his name.
Unfortunately, John’s story is not unique. Many individuals and businesses fall victim to similar scams each year, highlighting the importance of vigilance and education.
Expert Advice: How to Avoid Tax Scams
Be Skeptical of Unsolicited Contact
The ATO emphasises that they will never contact you through unsolicited email, SMS, or social media to ask for personal information or payment. If you receive such a message, do not engage. Instead, look up the ATO’s official contact numbers and verify the communication.
“Always verify unsolicited contact independently. Scammers often create a sense of urgency, but taking a moment to verify can save you from significant losses,” advises Sarah Johnson, cybersecurity expert at SecureNet Solutions.
Check for Authenticity
When in doubt, visit the ATO website directly. The ATO provides detailed information about ongoing scams and how to recognise them. They also offer a reporting service for any suspicious communication.
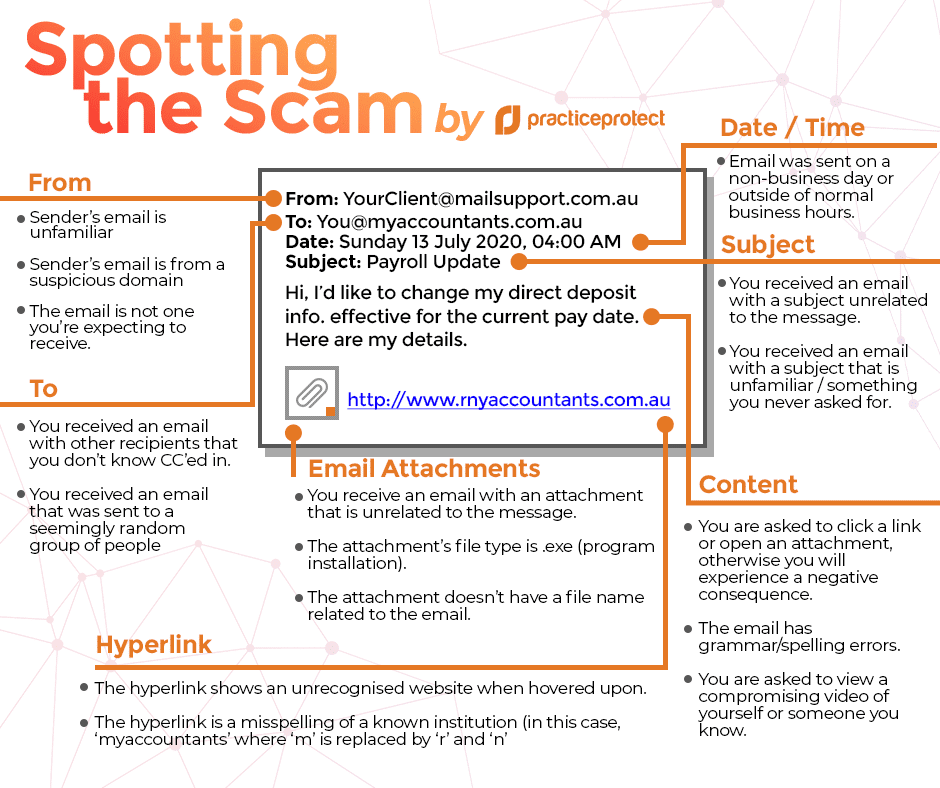
We’re attaching here, an Infographic put together by our Cybersecurity partner Practice Protect. This infographic highlights how you can spot an email scam.
“Legitimate organisations like the ATO will have secure methods for contacting you. Be wary of any communication that deviates from their standard procedures,” says Mark Harris, a fraud prevention specialist.
Use Strong Cybersecurity Practices
Ensure your devices are protected with up-to-date antivirus software, and be cautious about the information you share online. Regularly update your passwords and use two-factor authentication whenever possible.
“Cybersecurity is an essential layer of defense against scams. Protecting your digital footprint can prevent scammers from accessing sensitive information,” states Emily White, IT security consultant.
Proactive Measures by Authorities
The ATO and related authorities are continually working on new measures to combat scams. The creation of NASC and funding for the Australian Securities and Investments Commission (ASIC) and the Australian Communications and Media Authority (ACMA) to take down fake investment websites are steps in the right direction. The establishment of the SMS Sender ID register to stop scammers from spoofing trusted brand names has also been effective.
In addition, the ATO has a dedicated team monitoring for scams and assisting victims. They offer comprehensive resources and guidelines on their website to help the community recognise and report scams.
Statistics and Success Stories
The efforts of the ATO and NASC have led to significant achievements in scam prevention:
– Over 5,000 fraudulent websites were taken down in the final quarter of 2023.
– More than 100 million scam text messages were blocked during the same period.
– 31% increase in reports of ATO impersonation scams in May 2024 highlights the ongoing battle against scammers.
These statistics underscore the importance of remaining vigilant and the positive impact of coordinated efforts to combat fraud.
Conclusion
Tax time is a critical period for business owners and employees, making it a prime target for scammers. By staying informed about the latest tactics used by fraudsters and following expert advice, you can protect yourself and your business from falling victim to tax time scams. Remember to verify unsolicited contacts, check for authenticity, and practice robust cybersecurity measures. The collective effort of individuals and authorities is key to mitigating the risks posed by these persistent scams.
Understanding the Basics: Business Asset Depreciation
Business asset depreciation is what happens when business assets lose value over time.
It’s an often-forgotten cost of doing business – but it shouldn’t be. Here’s why depreciation is so important:
Costs you money – Depreciation accounting involves calculating how much value your assets lose each year. It can be listed as a loss and subtracted from your revenue.
Can reduce your tax bill – Because depreciation is a business cost, it can lower your tax bill. That’s why it’s important to know how much value you’re losing each year.
Affects the value of your business – If major business assets lose value, the overall value of your business is reduced. Inaccurate tracking could lead to overestimating your business value, making it harder to secure finance.
The ins and outs of business asset depreciation
Usually, only long-term or fixed assets can be depreciated, while consumable products aren’t included.
You also need to estimate the item’s lifespan and choose a method to calculate how its value declines over time.
Common methods include:
Straight line depreciation: the asset depreciates by the same amount each year, eventually reaching zero value.
Diminishing value depreciation: the value declines by a higher percentage in the first few years, then the rate of depreciation slows.
Units of production depreciation: the lifespan is calculated by the value delivered, not the time spent using the asset. For example, a business vehicle’s depreciation might be measured in kilometres travelled rather than age.
Accounting for depreciation in your business
When you’re just starting out, calculating depreciation can seem overwhelmingly complex. But, because it can lower your costs and help you track your business value, it’s worth making the effort.
If you’re not sure where to start, click here to get help from our expert accounting team now.
For more on our ‘Understanding the Basics’ series, see:
When running a business, it’s essential to understand the different types of taxes that apply. Depending on your business structure, you may be required to pay a variety of taxes. The most common taxes include:
Goods and Services Tax (GST)
Income Tax
Pay As You Go (PAYG) Withholding for employees
Payroll Tax
Excise Tax
In addition to these, your business might also encounter:
Fringe Benefits Tax (FBT)
Capital Gains Tax (CGT)
Property Taxes
Vehicle Taxes
State and Local Government Duties and Levies
Taxes Paid on the Business Activity Statement (BAS)
Once your business is registered for applicable taxes, you’ll report and pay many of them through your monthly or quarterly Business Activity Statement (BAS). Key taxes paid via BAS include:
GST: Your business collects GST from customers and pays it to suppliers, then pays the difference between the GST on sales and purchases.
PAYG Withholding: This applies to payments made to employees or suppliers who do not provide an Australian Business Number (ABN).
PAYG Instalments: Contribute towards your expected income tax bill.
Other taxes that may be included on the BAS (if applicable) are:
Fringe Benefits Tax (FBT) instalments
Fuel Tax Credits
Wine Equalisation Tax (WET)
Luxury Car Tax
State Revenue Office Taxes and Fees
Some business taxes are paid directly to your State Revenue Office. These can include:
Land Tax for property purchases
Payroll Tax (once your reportable wages exceed the state threshold)
Stamp Duty on property transfers
Income Tax for Businesses
At the end of the financial year, your business calculates income tax, factoring in any PAYG instalments already paid. By claiming tax deductions for business expenses, you can reduce your taxable income and lower your tax bill.
If your business makes a financial gain from disposing of assets, such as property or shares, you’ll pay Capital Gains Tax (CGT). This tax is part of your overall income tax. Income tax rates and calculations vary depending on your business structure, such as a sole trader, partnership, company, or trust.
Small Business Tax Concessions
If you’re a small business, you may qualify for tax concessions that reduce your tax liability. These concessions can apply to:
Asset write-offs
Primary producers
Fringe benefits
Start-up expenses
Additionally, there are Capital Gains Tax (CGT) concessions available to small businesses that can further reduce the tax payable.
Thinking of Starting or Changing a Business?
Before starting or making changes to your business, it’s crucial to plan for the taxes you’ll need to manage. Speak with a tax agent about adding or cancelling tax registrations, claiming concessions, and staying compliant with tax laws.
For more on our ‘Understanding the Basics’ series, see:
Australian residents pay personal income tax on all forms of income after a tax-free threshold of $18,200. The tax office calculate tax at four different rates according to how much income you earn each year, and the tax rate increases the more you make. The highest tax bracket applies to those with a taxable income of more than $180,001.
ATO taxes foreign residents, children, and working holidaymakers differently.
Income tax is the most significant type of tax the ATO collects, making up around half of all taxes they receive.
Types of Taxable Income
The ATO calculates tax on various forms of income, including employment, government support, investment, and business income.
Employment income includes; wages, salary, allowances, bonus payments, termination payments, some lump sum payments, fringe benefits, and superannuation contributions.
Government support includes all pension payments, allowances, carer support, and COVID-19 support payments. Some government support, such as disaster recovery payments, are tax exempt.
Investment income includes interest paid by financial institutions, share dividends, rent from investment properties, managed investment trusts, and capital gains from profit on selling assets. This also includes cryptocurrency gains.
Business income for sole traders is assessed as personal income, while business income for other entities such as companies is taxed separately to the individuals running the business entity.
Annual Tax Return
You have to declare all types of income, Australian and foreign. Any income received in foreign currency needs to be converted to Australian dollar value.
Most people need to lodge a tax return with the Australian Taxation Office each year by 31 October. If you have a tax agent lodging on your behalf, you’ll get an extension.
Your employer withholds tax from your wages or salary each pay period and pays the ATO on your behalf. If you’ve earned more money from other sources, such as investments or a side hustle, you might end up with a tax bill in addition to what has been withheld from your pay. When we calculate your taxable income, we’ll let you know in plenty of time if you have to pay more.
Make the Most of Allowable Deductions
Allowable deductions vary significantly according to the type of income you have earned. You can’t claim private expenses or anything that an employer has reimbursed.
Common deductions include home office, tools and equipment, accounting fees, donations, personal super contributions, and vehicle expenses. However, it’s best to check with us as you may be able to claim other expenses such as education, cleaning, or professional memberships.
When preparing your tax return, we will include any allowable offsets, rebates, or concessions that may apply to your situation to reduce your tax bill. We’ll also check that you’ve included all allowable deductions for your situation.
Click here to make an appointment with one of our tax accountants.
For more on our ‘Understanding the Basics’ series, see:
A capital gain (or loss) occurs when an asset is sold. The difference between the purchase price and the sale price is the gain or loss. Capital gains tax (CGT) applies to money you have made from selling an eligible asset.
Capital gains tax events occur when an asset is sold, or other triggers arise, such as the loss, theft, or destruction of an asset, or creating contractual or other rights to an asset.
Not all assets are subject to CGT. Common exemptions include the primary residence or family home, granny flats, cars and motorcycles, personal use assets such as boats, furniture, household items, or loans to family and friends. Many types of lump sum payments are also not subject to CGT, and business sales may also be exempt depending on the circumstances.
Most property is subject to CGT, including land, commercial premises, rental properties, holiday houses, and hobby farms. CGT also applies to shares, investments, cryptocurrency, many collectables, foreign currency, and intangible assets.
There are special rules for some specific situations, for example, inheriting assets, relationship breakdown, foreign residents, insurance, or compensation payments.
How is the Tax Calculated?
Tax is calculated on the net gain of an asset sale. Tax is payable on the difference between the purchase price and sale price, less any discount allowed.
The type of CGT event affects how and when capital gains tax is calculated. For example, if an asset is destroyed in an accident, the CGT event occurs when the insurance payout is received.
Good record keeping is key to working out capital gains tax accurately. Ensure you keep all documents related to; asset purchases, including contracts, expenses valuations, and disposal.
CGT is calculated when completing your individual, business, or self-managed super fund tax return and is included in the income tax assessment.
Talk to us to ensure you’re claiming all you’re entitled to and not paying more tax than you should. We’ll make sure you’re receiving any exemptions, discounts, or small business concessions allowed.
For more on our ‘Understanding the Basics’ series, see:
Many people new to running a business and employing people are unsure about the difference between PAYGI and PAYGW. They are not the same thing!
PAYG stands for ‘pay as you go’. This is the means the ATO uses to obtain tax payments from both employees and business owners. Paying tax ‘as you go’ throughout the year means you don’t have to pay it in one lump sum at end of tax year.
PAYG Withholding for Employees Income Tax
PAYG withholding (PAYGW) refers to the income tax an employer withholds from employees’ gross wages to meet their personal income tax liabilities. Employers are required to remit the employees’ withheld tax to the ATO each month or quarter. They do this with the business activity statement (BAS) or the monthly instalment activity statement (IAS).
PAYG withholding applies to employers’ payments to employees, directors, office holders, and labour-hire workers. It can also be withheld from non-employees; contractors with a voluntary withholding agreement, some payments to foreign residents and payments to suppliers where an ABN has not been quoted.
PAYG Instalments for Business Income Tax
If you run your own business, you’ll need to plan for income tax payments once you make more than the taxable threshold. PAYG instalments (PAYGI) allow you to pay an amount towards an expected tax bill. Amounts are based on business or investment income from the previous tax year. Once you complete your tax return, the amounts already paid are offset against the total amount of tax due. You will then receive either a bill for extra tax, or if you have paid too much, you will receive a refund.
Usually, when starting in business, you don’t pay any tax instalments until you have completed the first year’s tax return. However, if you’re new to business, you can voluntarily enter into the PAYG instalment system to start contributing towards your next tax bill. This is worth considering if you have done better than expected in your first year!
You can pay PAYG instalments using the ATO determined amount based on information in the last tax return (instalment amount) or using the ATO defined percentage rate applied to your income (instalment rate). The first method is the simplest; however, if your income varies a lot from one quarter to another, it’s better to use the instalment rate. Then you know you have put aside the correct amount based on your actual income.
PAYG Planning for Cash Flow
Suppose you’re new to business or considering employing people soon. In that case, you’ll need to plan for PAYG instalments and possibly PAYG withholding (PAYGI and PAYGW). Then you can meet your ATO tax reporting and paying obligations. Planning ahead means you’ll never be caught short with cash flow difficulties. Talk to us to learn more about income tax responsibilities as an employer and business owner.